Tax Classification Must Be Based on the Form of Goods at the Stage of Sale, Not on Their End Use
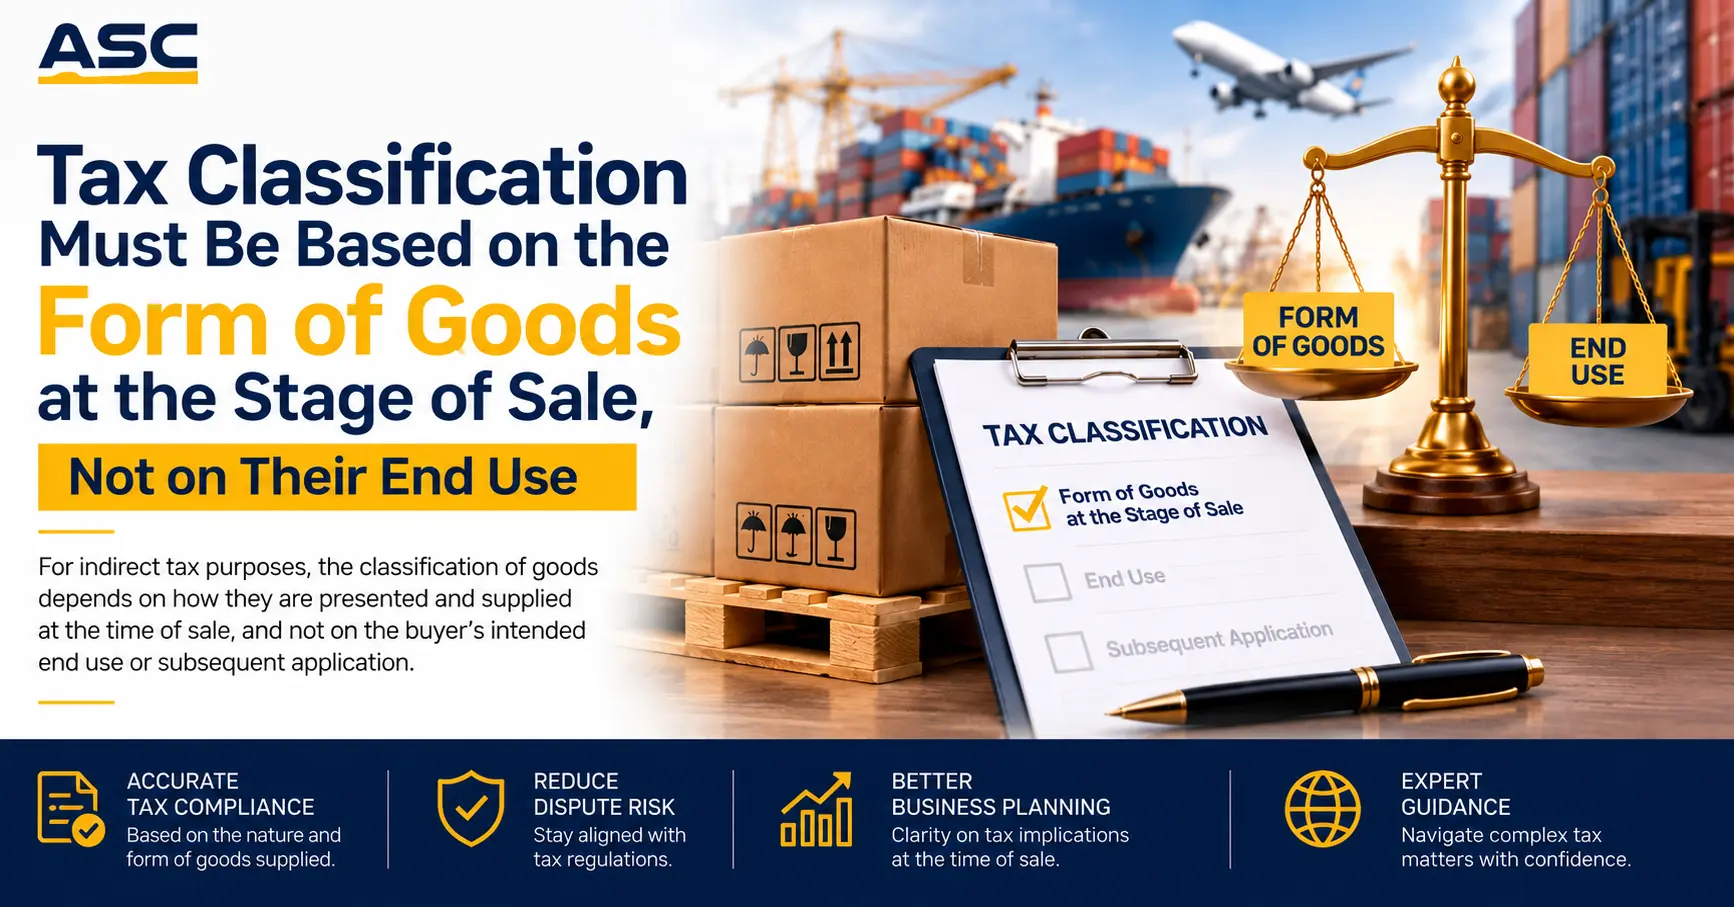
The Supreme Court of India, in its judgment dated 5 October 2026 in Addl. Commr. Commercial Tax & Ors. v. Cadila Health Care Ltd & Anr. (2026 INSC 1078), has settled an important question of tax law: when a product can be classified under more than one taxing entry, should classification depend on the physical form in which the good is sold, or on how the consumer ultimately uses it? A Division Bench of Justice Manmohan and Justice Arun Palli held that it is the form of the good at the point of sale, not its eventual end use, that determines its tax classification.
Background of the Dispute
The case arose from a classification dispute concerning two products, 'GRD Powder' and 'GRD Mix', manufactured and marketed by Cadila Health Care Ltd. The dispute traced back to the Assessment Year 1997-1998 under the Madhya Pradesh Commercial Tax Act, 1994.
The tax department (the Appellants) contended that these products, sold in powder and biscuit form, ought to be classified as 'Non-Alcoholic Drinks and Beverages' under Entry 20(ii), Part IV, Schedule II of the 1994 Act, attracting a higher tax rate of 10%. Their reasoning rested on the packaging instructions, which encouraged consumers to dilute the powder with milk or water and "enjoy the preparation either hot or cold" — framing the product, in substance, as a health drink.
Cadila, on the other hand, argued that since the goods were sold across the counter in solid form — as powder and biscuit — they could not be shoehorned into an entry meant for liquid beverages. According to the company, such goods fell outside every specific entry and were therefore taxable only at 8% under the residuary entry of Schedule II.
The Madhya Pradesh High Court had earlier ruled in favour of Cadila, upholding the 8% residuary classification. The Revenue authorities appealed this finding to the Supreme Court.
The Core Legal Issues
The Supreme Court identified two central questions for determination:
- Whether the taxing authorities must levy tax based on the form of the goods at the time of sale, or on the end product into which the goods are eventually converted by the consumer.
- Whether 'GRD Powder' and 'GRD Mix' could properly be classified as 'Non-Alcoholic Drinks and Beverages', or whether they fell within the residuary entry.
Arguments Advanced by the Parties
Counsel for the tax authorities urged the Court to apply three interpretive tools used in classification disputes: the "common use and functional character test" from Atul Glass Industries v. Collector of Excise (1986); the "basic nature of the good" test, independent of manufacturing process, relying on Indian Aluminum Cables Ltd. v. Union of India (1985); and the "popular meaning or common parlance" test. On this basis, it was argued that the functional character of GRD Powder and GRD Mix was that of a beverage, and that tea and coffee — though sold in powder form — have long been taxed as beverages. Reliance was also placed on Pioma Industries v. State of Kerala (2008) and Hamdard (Wakf) Laboratories v. Commissioner, Commercial Tax, U.P. (2026), which held that the word "including" in a taxing entry expands its scope.
Counsel for Cadila countered that the charging provisions of the 1994 Act confine taxation strictly to goods expressly specified in Schedule II, and that any good not specifically enumerated must fall into the residuary entry rather than being forced into an inapposite specific entry to attract a higher rate. Entry 20(ii) made no reference to "use" or "adaptation" of the good, and under Dunlop India Ltd. v. Union of India (1976), end use is wholly irrelevant to classification. Reliance was also placed on Hamdard Wakf Laboratories v. Collector of Central Excise (1999), which held that a "beverage" is fundamentally a liquid for drinking.
The Supreme Court's Reasoning
The Court began by reaffirming the settled principle that taxing statutes must be strictly construed, with no scope for the Court to read in meanings beyond the plain language of the provision.
Applying this principle, the Bench held that the taxable event is the act of supply, and the tax incidence must be determined strictly by the nature and form of the good as it exists at that moment of sale — not by what the consumer subsequently chooses to do with it. The Court illustrated this with a practical example: a protein powder sold as a powder attracts the tax applicable to powders, while a ready-to-drink beverage such as bottled cold coffee attracts the tax applicable to beverages. The fact that a consumer might later mix a powder with milk to create a drink — or equally, use it to prepare a solid sweet such as barfi — does not retrospectively alter the nature of what was actually sold.
The Court also undertook a textual analysis of Entry 20(ii), noting that "beverages" there is accompanied by words such as "syrups, cordials, distilled juices, ark and essences" — all denoting liquid substances. Applying the rule of ejusdem generis, the Court held that "beverages" must take its colour from this company of liquid-denoting words, and cannot be stretched to cover a good that exists, at the point of sale, as a solid powder or biscuit.
Significantly, the Court clarified that the common parlance, functional character, or basic nature tests cannot be deployed to smuggle in an "end use" concept where statutory language is clear and unambiguous. It also distinguished the precedents cited by the Revenue: in Pioma Industries, the relevant entry had expressly included "powders, tablets and concentrates" by way of a deeming explanation — absent from Entry 20(ii) here. In Hamdard (Wakf) Laboratories (2026), the product in question — sharbat — existed in liquid form at sale, unlike GRD Powder and GRD Mix.
Conclusion and Significance
Since GRD Powder and GRD Mix existed in solid, powdered form at the time of the taxable event, the Court held they could not be classified as "beverages" under Entry 20(ii), and therefore correctly fell within the residuary entry attracting the lower tax rate. The appeals filed by the tax authorities were accordingly dismissed.
The ruling carries implications for commercial tax disputes well beyond this case. It establishes that classification under fiscal statutes must be resolved by reference to the physical form of goods as they exist at the point of sale, insulating manufacturers and traders from reclassification based on probable downstream consumer use. For any product with multiple possible end uses — powders, concentrates, or mixes consumable in different forms — this judgment offers a clear anchor: look at what was actually sold, not at what it might become.
Leave a Reply